Life Company Loans for Commercial Real Estate
Life company loans range from $5M to $100M+ at 6.15% to 6.75% fixed, typically 10 to 25 years, up to about 65% LTV, non-recourse. Desks quote spreads over Treasury: tight execution runs 120 to 180 bps, so apply the current bond yield to estimate your rate. Best for institutional multifamily, industrial, and credit net lease in primary markets. Commercial Lending Solutions accesses the full life company market through two channels: direct open-market desks (New York Life, Northwestern Mutual, MetLife, Manulife, PGIM) and correspondent programs. The named lender table below shows the desks and programs.
Recent life company closings.
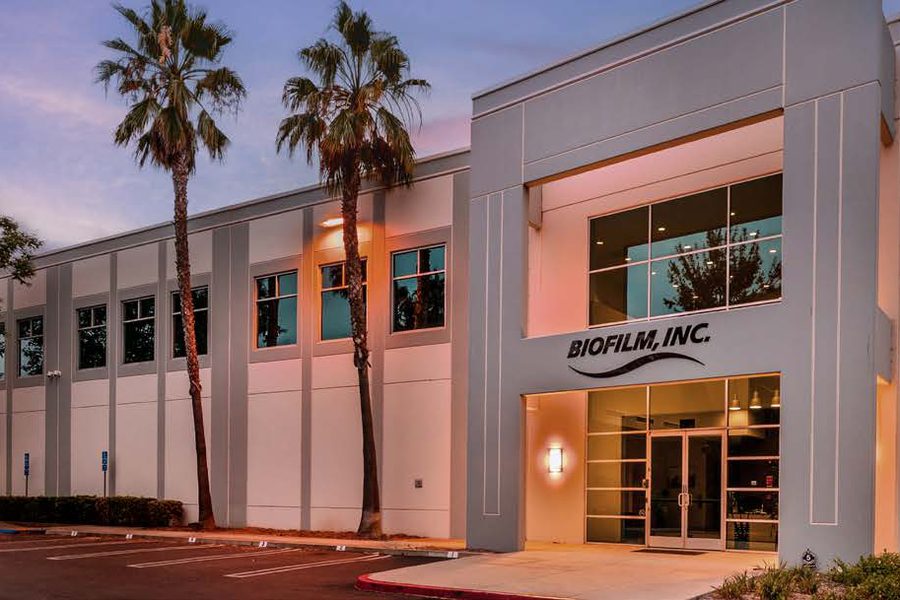
Industrial R&D
Single-tenant industrial R&D headquarters placed with a life insurance company lender at 225 bps over the 5-year Treasury: a 5-year fixed, 30-year amortization structure that bank and CMBS quotes could not match on a non-recourse basis.
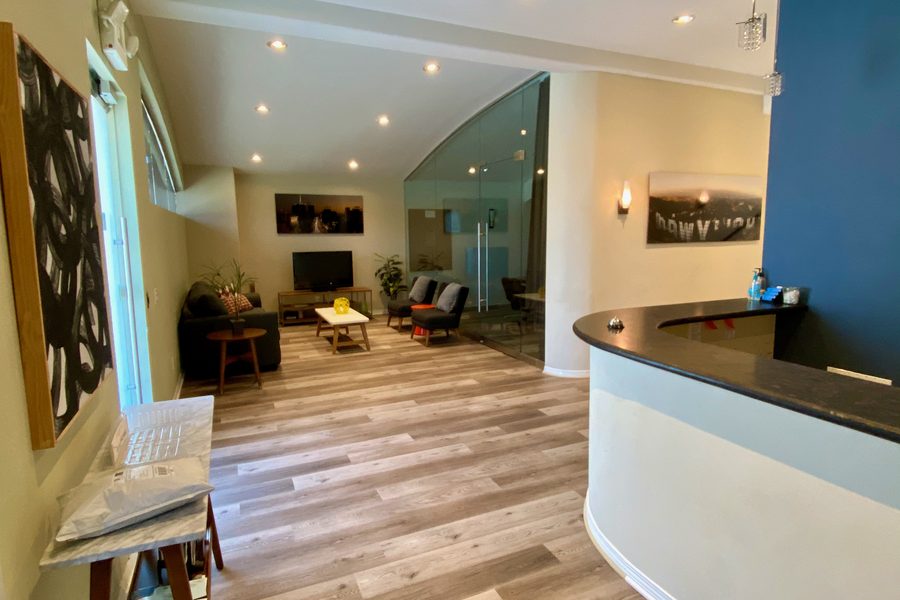
Creative Office / Mixed-Use
Post-production and creative office campus across from Universal Studios financed at 285 bps over the 3-year Treasury, 6-year term (3+3) with 25-year amortization, structured around short-term media leases with a master-lease credit enhance from the sponsor group.
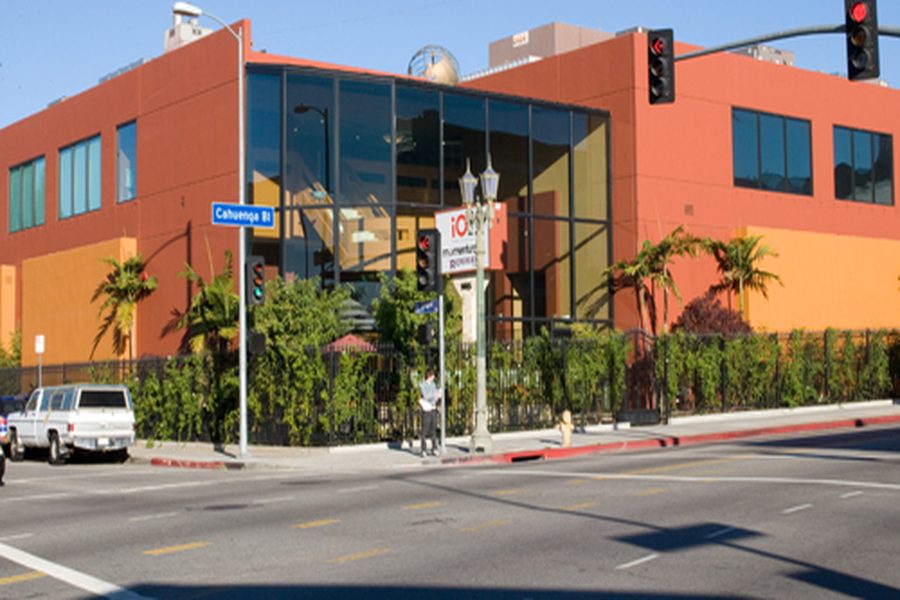
Special-Use Office
Special-use office building on Cahuenga financed at 250 bps over the 3-year Treasury: a 6-year term (3+2+1) with 25-year amortization tailored to a single-tenant media occupant.

Office / Flex
Office/flex building near the Burbank media corridors placed with a life company at 260 bps over the 5-year Treasury: an 8-year term (5+3) with 25-year amortization for a long-term hold sponsor.
Spreads shown are actual executed rates over matching-term Treasuries. Structures, lender selection and pricing vary by asset.
Have a deal a life company should see?
Share the property and financing request. We will respond with the desks whose current appetite fits, and indicative terms for each.
Get indicative terms →Life company loan terms at a glance
- Loan Amount
- $5M to $100M+
- Term
- 10 to 25 Years
- Rates
- 6.15% to 6.75%
- LTV
- Up to 65% LTV
- Amortization
- 15 to 30 Years; 10-year options; interest-only available
- Recourse
- Non-recourse standard; structures negotiable
- Typical Spread
- 120 to 180 bps over UST
These are starting points, not the shelf. Amortization as tight as 10 or 15 years, interest-only periods, and structured executions are all on the table when the deal supports them. That flexibility is the reason sponsors bring us life company placements.
Terms are indicative and subject to property, sponsorship, market conditions, and lender underwriting. Price a deal at today's yields with the life company spread calculator.
$16,250,000, an actual executed life company spread. See the track record →
The desks we place with.
Program parameters for nine life company lenders. Each links to a dedicated page with qualification guidance and current spread context.
| Life company lender | Loan size | Terms & leverage | Programs | Best fit |
|---|---|---|---|---|
|
|
$25M–$300M+ (portfolios higher) | 3–30 years; floating ≤7 years Up to 80% LTV, 1.30x+ DSCR |
Permanent fixed; floating-rate; bridge/CTP; subordinated debt from $20M | $25M+ institutional multifamily, industrial, office in primary markets |
 Northwestern Mutual |
$30M–$500M | 5–25 years; fixed over UST or floating over SOFR Up to 75% LTV, 1.25x+ DSCR |
Permanent fixed/floating; JV equity available; in-house appraisal (free to borrower) | $30M+ long-term holds wanting maximum rate certainty |
 MetLife |
$10M–$200M+ per property | 3–30 years; fixed and floating ~65% LTV typical, higher select |
Permanent; bridge; construction; mezzanine; interest-only options | $10M–$100M core plus with flexible structure needs |
 Manulife |
$10M–$300M+ (US) | Fixed-rate core; forward commitments Not published; deal-by-deal |
Permanent; mezzanine; B-notes; participations; forward commitments | $10M+ sponsors wanting one desk for debt plus mezz |
 PGIM |
Not published (top-5 national originator) | Core and core-plus; structured debt Deal-by-deal |
Core debt; core-plus; structured; agency overlays | Institutional-scale portfolios and structured executions |
 Principal |
$10M–$100M+ per transaction | Under 3 to 30 years Deal-by-deal |
Commercial mortgage loans; construction-permanent program | $10M–$50M deals wanting construction-perm in one close |
 Guardian |
Not published | Fixed-rate core Deal-by-deal |
Real estate debt investments; core fixed | Western US stabilized assets, relationship-driven execution |
 Symetra |
$1M–$20M+ (program flexes for strong assets) | 5–10 year structures; 3+3, 5+3, 5+2 resets Deal-by-deal |
Fixed-rate permanent; special-use assets; single-tenant strength | $5M–$20M stabilized and special-use, especially California |
 Protective |
$3M–$50M per asset | Fixed-rate permanent Up to 75% LTV |
Permanent fixed-rate on stabilized income property | $3M–$50M stabilized multifamily and commercial |
Program parameters verified from lender-published materials, September 2026. Rates and spreads are indicative and set deal-by-deal; terms shown reflect recently executed transactions and current desk guidance.
The life company playbook.
Four guides, each doing one job well. Written the way we underwrite: specific, dated, no filler.
Life company loan rates & spreads
Current leverage-tier rate table, how desks quote spreads over Treasury, and the math to price any deal yourself.
Open the rate table →How to qualify for a life company loan
The box a desk needs you in, the documents to have ready, and a realistic timeline from term sheet to close.
See the qualification box →How we run a life company placement
Sourcing, matching to current appetite, diligence coordination, and closing, with a weekly update while it is in flight.
Walk the process →What gets a life company loan approved
Sponsorship depth, DSCR, leverage, market tier, and prepay structure, ranked by what actually moves a credit committee.
See the approval factors →Life Company financing, clarified.
The final structure depends on the asset, sponsorship, and market. These are the starting parameters we discuss most often.
A life insurance company loan is a commercial mortgage funded directly from a life insurer's general account. Life companies hold these loans as long-duration fixed-income investments, which allows them to offer the most competitive fixed rates and the longest terms available in the private commercial mortgage market.
Life companies favor institutional-quality stabilized assets including Class A office, industrial, anchored retail, multifamily, and premium net lease. They generally prefer primary and strong secondary markets, low leverage, and strong sponsorship. Properties with complex stories are usually a better fit for CMBS or banks.
Life insurance company rates typically range from 6.15% to 6.75% for stabilized assets, making them the tightest-priced option in the private commercial mortgage market. Rates are quoted as a spread over the matching-term treasury and are generally the lowest available for borrowers who fit the box.
Life companies typically cap leverage at 60% to 65% LTV, occasionally reaching 70% for exceptional deals. The low leverage is a deliberate tradeoff for the tight pricing, long term, and prepayment flexibility that life companies offer.